
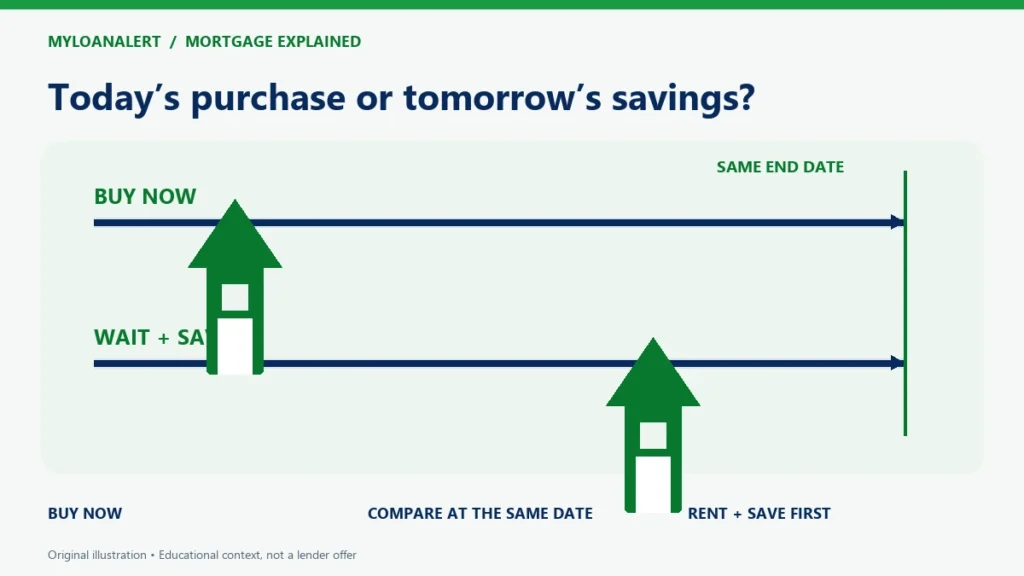
The short answerWaiting can improve your cash position and reduce the amount you need to borrow, but it also means paying rent while saving. Future prices and rates could change either way. Compare both paths at the same end date using several scenarios, not a prediction that one path must win.
You could buy with the money you have, or wait until the down payment feels more comfortable. It is a real tradeoff. Waiting is not automatically wasting time, and buying sooner is not automatically getting ahead. Put a specific savings period into the comparison so you can see what waiting would actually mean.
Give the waiting plan a date and an amount
Choose how many months you would wait and how much you could realistically save each month. Account for rent and ordinary living costs rather than assuming every spare dollar reaches the down payment.
Keep money for closing and a reserve separate from the down-payment target. A bigger down payment is only helpful if the complete cash plan still works.
Use a real quote for the buy-now case
Record the current purchase price, quoted rate, loan term and estimated ownership costs. Ask the lender how the down payment affects mortgage insurance and available pricing.
For the future case, label the rate and price as assumptions. Your future lender offer may differ from both today’s quote and the number entered in the calculator.
Compare both paths at one finish line
A fair comparison includes the renting period before the delayed purchase. It should also show the cash required, monthly ownership cost and remaining debt at the same final date.
Otherwise, you might accidentally compare five years of owning now with five years of owning after waiting, leaving out the waiting year itself.
Try a few futures
Run a flat-price scenario, a higher-price scenario and a less favorable rate. Also consider what happens if you save less than planned. These tests show which assumptions the decision depends on.
When your main question is whether to own at all, use the rent-versus-buy comparison. When it is whether the monthly budget works, use housing affordability. Each tool answers a different question.
A simple example
Saving $700 a month for 18 months adds $12,600 before interest or withdrawals. If rent is $2,000, that period also includes $36,000 in rent. Those totals do not prove buying now is better; they are inputs to compare with ownership costs, cash needs and debt under each path.
Illustrative assumptions, not current lender pricing or promised savings.
Questions people ask
Should I wait until I have a 20% down payment?
Do not use a single percentage as the whole decision. Ask about available loan options and compare the complete budget, insurance, cash buffer and costs.
Does the calculator forecast home prices?
No. It uses your assumptions to illustrate possible outcomes. Try more than one future price and rate.
Try this with your numbers
Use your lender’s quote and your own assumptions. No signup is needed for the calculator.
Compare buying now with waiting →
See the free account · Compare more with Plus — $30 USD/year
New signup is coming soon. Existing accounts can save an offer or goal. Paid checkout is coming soon. Automatic monitoring and email alerts are not active yet.
Sources and further reading
Educational information and estimates only. Confirm loan terms and eligibility with your lender or servicer. MyLoanAlert does not originate or approve loans. Read our disclosures.