
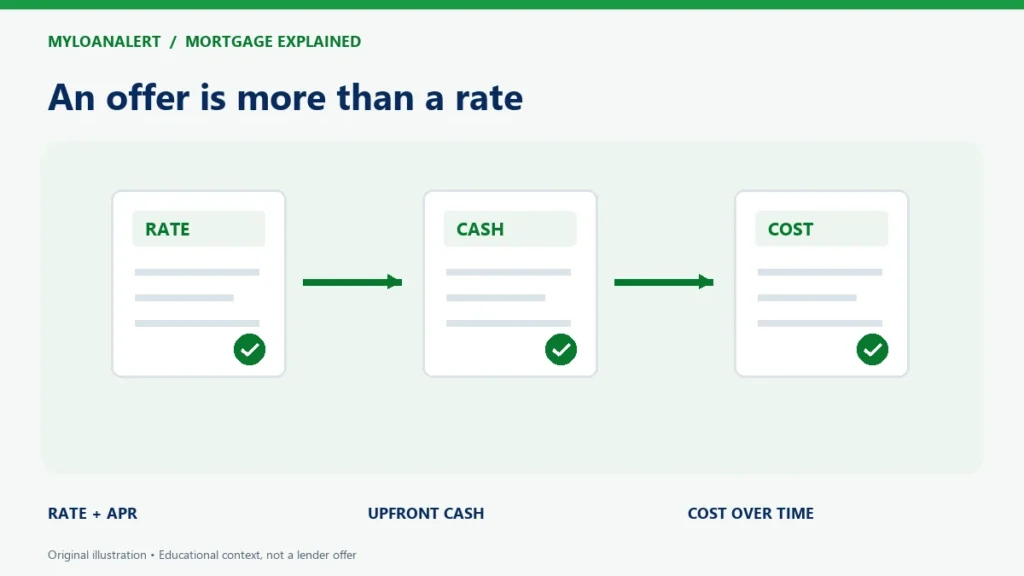
The short answerCompare the same loan amount and loan type, then look at the payment, lender fees, credits and borrowing cost over the time you expect to keep the loan. A lower rate alone does not settle the question.
Two lenders send you estimates. One rate looks better, but the other needs less cash at closing. Which one is cheaper? That is exactly why a mortgage comparison needs more than a glance at the first page. Start by putting the offers on the same footing. Then separate three questions: What can I afford each month? What must I bring to closing? What will this loan cost over my time frame?
Start with the same loan
Check the amount borrowed, repayment term and whether the rate is fixed or adjustable. Compare estimates issued close together and check whether each rate is locked. A quote from last week and a quote from this morning may reflect different market conditions.
If the loan amounts differ because fees are being added to one balance, make a note of it. Financing a fee changes both the money borrowed and the interest you may pay on it.
Separate payment, fees and cash to close
The total housing payment and the loan’s borrowing cost answer different questions. Taxes and homeowners insurance matter to your budget, but a lender estimating a smaller tax bill has not necessarily offered a cheaper mortgage.
Look for origination charges, required services and lender credits. Keep the down payment and prepaid or escrow amounts separate from lender pricing. Ask about any unexplained difference rather than treating every dollar due at closing as a lender fee.
Choose a time frame that fits your plans
Compare both loans over the same number of years. If you may move in five years, the full 30-year total is useful context, but it is not your only comparison. Look at interest, fees and debt still owed at your selected end date.
Try a shorter and a longer stay too. A result that changes when you move the end date tells you something useful: the tradeoff depends on how long you keep the mortgage.
Bring these questions to your lender
- Which charges can change before closing?
- What rate could I get with no discount points?
- Are fees paid in cash or added to the loan?
- How long is the rate locked, and what would an extension cost?
- Why do the tax or insurance estimates differ?
Use the Offer Guide to keep track of unanswered questions. A calculator cannot fill in a missing lender term for you.
A simple example
Suppose Offer A saves $60 a month but requires $2,400 more in fees. Dividing $2,400 by $60 gives a simple 40-month payment break-even. That quick check leaves out balance differences and other costs. Use the full comparison before deciding that the lower payment wins.
Illustrative assumptions, not current lender pricing or promised savings.
Questions people ask
Is the lowest APR always the cheapest offer?
APR is useful context, but it does not replace comparing actual cash needs and costs over your expected loan-holding period. Check the assumptions, particularly for an adjustable-rate loan.
Can I compare an estimate with a verbal quote?
You can make a preliminary comparison, but mark missing information clearly. Ask for a written estimate with the same loan details before relying on the result.
Try this with your numbers
Use your lender’s quote and your own assumptions. No signup is needed for the calculator.
See the free account · Compare more with Plus — $30 USD/year
New signup is coming soon. Existing accounts can save an offer or goal. Paid checkout is coming soon. Automatic monitoring and email alerts are not active yet.
Sources and further reading
Educational information and estimates only. Confirm loan terms and eligibility with your lender or servicer. MyLoanAlert does not originate or approve loans. Read our disclosures.