
MYLOANALERT · LEARN
Construction & Renovation Guides
Plan for draws, delays, incentives and the permanent mortgage. Compare the financing independently from the building or renovation project.
Construction Loans: Plan for the Build and the Permanent Mortgage
Construction financing often funds work in stages and can have a different payment structure from the eventual mortgage. Compare the construction phase, conversion requirements, fees and what happens if the project is delayed.
Read the guide : Construction Loans: Plan for the Build and the Permanent MortgageShould You Use the Builder’s Lender? Compare the Incentive and the Loan
Compare the preferred lender with outside written offers after accounting for any incentive. A closing-cost credit or temporary payment reduction does not by itself prove the cheaper loan.
Read the guide : Should You Use the Builder’s Lender? Compare the Incentive and the LoanFinancing Home Improvements: Keep the Project and Loan Budgets Separate
Compare savings, unsecured credit and home-secured options using actual costs and repayment terms. A cash-out refinance changes the first mortgage; a home-equity loan adds another obligation.
Read the guide : Financing Home Improvements: Keep the Project and Loan Budgets SeparateMore guides and comparisons
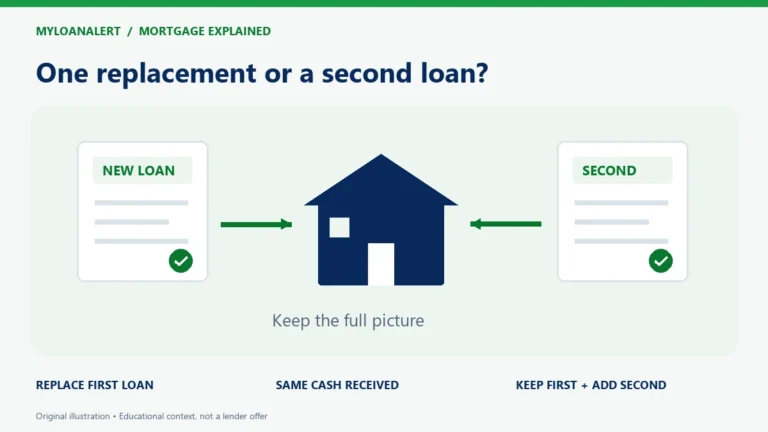
Cash-Out Refinance or Home-Equity Loan? Protect the Mortgage You Already Have
Compare a cash-out refinance with a fixed home-equity loan using the same cash received. Include your existing mortgage, both payments, fees and remaining debt.
Read the guide : Cash-Out Refinance or Home-Equity Loan? Protect the Mortgage You Already HaveBring your numbers to the next step
Use a calculator for an estimate or the offer guide for a written quote. Review the assumptions and confirm missing details with the lender.
Educational guides by MyLoanAlert. Source checks: October 12, 2026. Guides cite their sources and explain their limits. Program rules, rates and individual eligibility can change.