
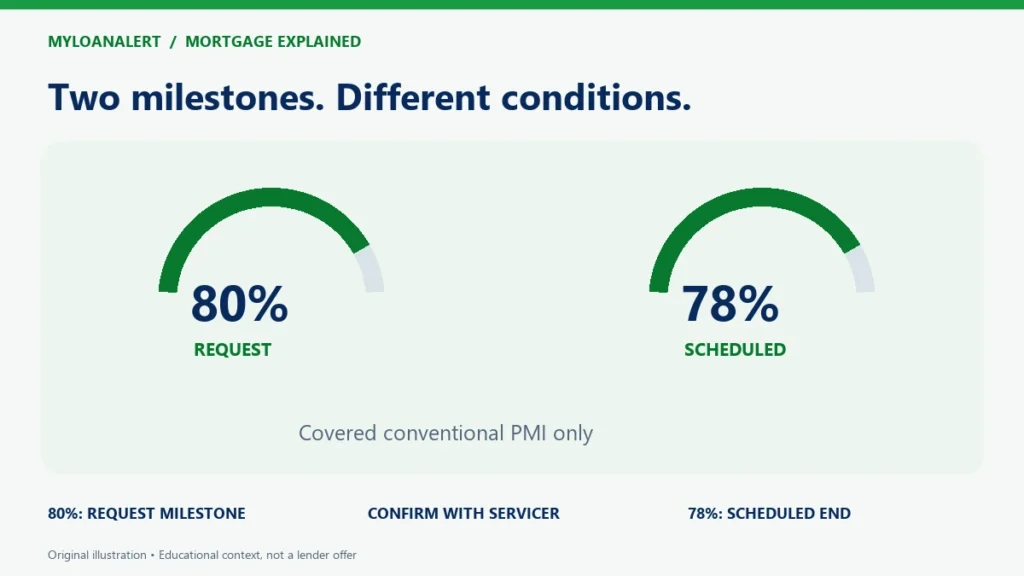
The short answerFor many covered conventional mortgages, you can request PMI cancellation when the balance reaches 80% of the home’s original value, subject to conditions. Automatic termination generally follows the scheduled 78% date if payments are current. FHA, VA and lender-paid insurance follow different rules.
If you see mortgage insurance on your statement every month, it is worth finding out what could make that charge end. But “I have 20% equity” and “my insurance must stop today” are not the same statement. The loan type, original value, payment history and servicer requirements all belong in the conversation.
Confirm which insurance you have
Start with the loan documents or ask your servicer: Is this borrower-paid private mortgage insurance on a conventional loan? The PMI calculator is designed for that kind of question.
Do not apply its milestones to FHA mortgage insurance, VA loans or lender-paid insurance. Ask for the rules that fit your actual loan instead.
Find the original-value figure
For the rules described here, original value generally uses the lower of the purchase price or the appraisal at purchase. For a refinance, the appraisal at that refinance generally supplies the original value.
That is different from guessing what the home would sell for today. A current-value cancellation request may involve separate investor or servicer standards.
Treat an estimate as a conversation starter
A calculator can estimate when the balance might reach a milestone. Extra principal may move the request opportunity earlier. It does not establish that all cancellation conditions have been met.
Ask about the written request, payment history, junior liens, evidence of property value and any required fee. Keep the servicer’s response with your loan records.
Check the scheduled date too
Automatic termination generally uses the scheduled balance reaching 78% of original value, rather than whichever date your actual balance happens to reach 78%. You generally need to be current on payments.
There is also a midpoint termination rule for covered loans. Your disclosure and servicer can confirm the dates and conditions that apply. If the date seems wrong, ask for the calculation in writing.
A simple example
With an original value of $300,000, 80% is $240,000 and 78% is $234,000. Those are reference balances, not unconditional cancellation promises. Enter your original value, mortgage balance and schedule, then ask your servicer to confirm the applicable date.
Illustrative assumptions, not current lender pricing or promised savings.
Questions people ask
Does a higher home value automatically remove PMI?
No. A current-value request can involve separate rules, valuation requirements and costs. Contact the servicer before relying on an estimated equity percentage.
Will this remove FHA mortgage insurance?
No. FHA mortgage insurance follows different rules. The conventional PMI milestones should not be used as an FHA cancellation guide.
Try this with your numbers
Use your lender’s quote and your own assumptions. No signup is needed for the calculator.
See the free account · Compare more with Plus — $30 USD/year
New signup is coming soon. Existing accounts can save an offer or goal. Paid checkout is coming soon. Automatic monitoring and email alerts are not active yet.
Sources and further reading
Educational information and estimates only. Confirm loan terms and eligibility with your lender or servicer. MyLoanAlert does not originate or approve loans. Read our disclosures.